Skip to main content
Toggle navigation
Advanced search
Home
Collections
About
About Digital Collections
Terms of use
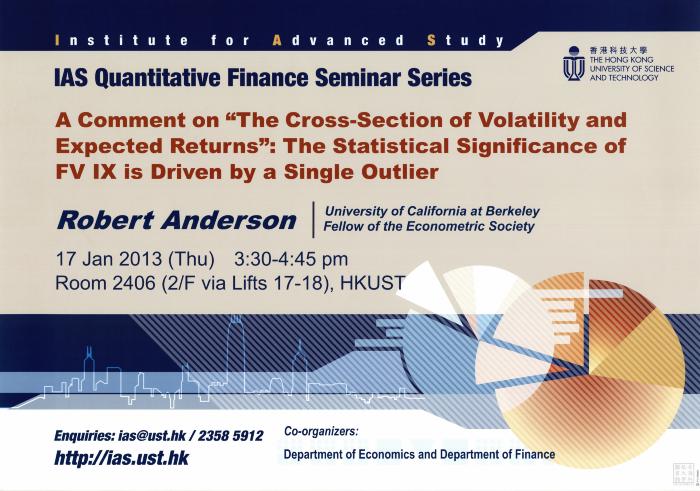
A Comment on "The Cross-Section of Volatility and Expected Returns": The Statistical Significance of FV IX is Driven by a Single Outlier
Collection
HKUST Posters
Additional titles
IAS Quantitative Finance Seminar
Author
Hong Kong University of Science and Technology.|bInstitute for Advanced Study
Date
2013
Note
Robert Anderson
Call number
RG8.15
Statement of responsibility
Institute for Advanced Study
URL
https://digitalcollections.hkust.edu.hk/Detail/objects/x000857